
Across the trailing 90 days — August 3 to November 1, 2026 — a daily scraper captured 4,721 public price observations covering 69 compounds, 330 distinct SKUs, and 8 anonymized vendors. Normalized to a per-mg basis, the spread between the cheapest and most expensive well-tracked compounds runs from NAD+ at a $0.10/mg median to AOD-9604 at $11.00/mg — a roughly 106× range inside a single market.
The headline number for anyone planning a purchase is the aggregate stockout rate: 6.2% of vendor-day observations showed a product unavailable, down from 8.3% in the prior window and concentrated in SLU-PP-332 (27.0% OOS), GHK-Cu (21.7%), adamax (20.6%), and SS-31 (17.9%). Prices in this market move less than availability does.
This report is the 90-day analysis; for today's per-mg prices across these vendors, see the continuously updated live price index, which also offers the full dataset as a CSV download.
Compare Top Peptides
Best vendor pricing, COA verified, with active discount codes
Methodology
Research-context information only. This report describes industry pricing patterns observed over a trailing 90-day window. Nothing in this report is medical advice, financial advice, or a recommendation to buy or sell any peptide. Peptides discussed are research compounds; most are not approved by the FDA for human use. Consult a licensed physician for personal medical decisions.
Vendor identities are anonymized to maintain editorial independence. Pricing data is normalized to a per-mg basis. All data sourced from publicly-listed vendor prices captured daily during the data window.
The pipeline is simple. A daily scraper visits each tracked vendor's product pages, parses the listed price and stock status, and writes a snapshot row to an offer_price_history table. Each row is one (vendor, SKU, captured-at) tuple. We do not use cached data, retail aggregators, or rumored prices — every observation is a public price visible to any buyer on the day it was captured.
Per-mg normalization is computed as price_cents ÷ (mg_per_vial × vial_count) so a 10-vial bundle of 5mg vials at $400 normalizes to the same $8.00/mg as a single 10mg vial at $80.
For this report, vendors are renamed Vendor A, Vendor B, Vendor C, … using a stable SHA-1 hash of their internal id. The hash sort means a given vendor keeps the same label across successive monthly refreshes — but you cannot reverse-engineer the label back to the vendor without access to the source database. That is intentional.
Median and range figures below are computed from in-stock observations only unless labeled "full window"; stockout rates and volatility figures are computed from all observations.
Cross-Peptide Trends
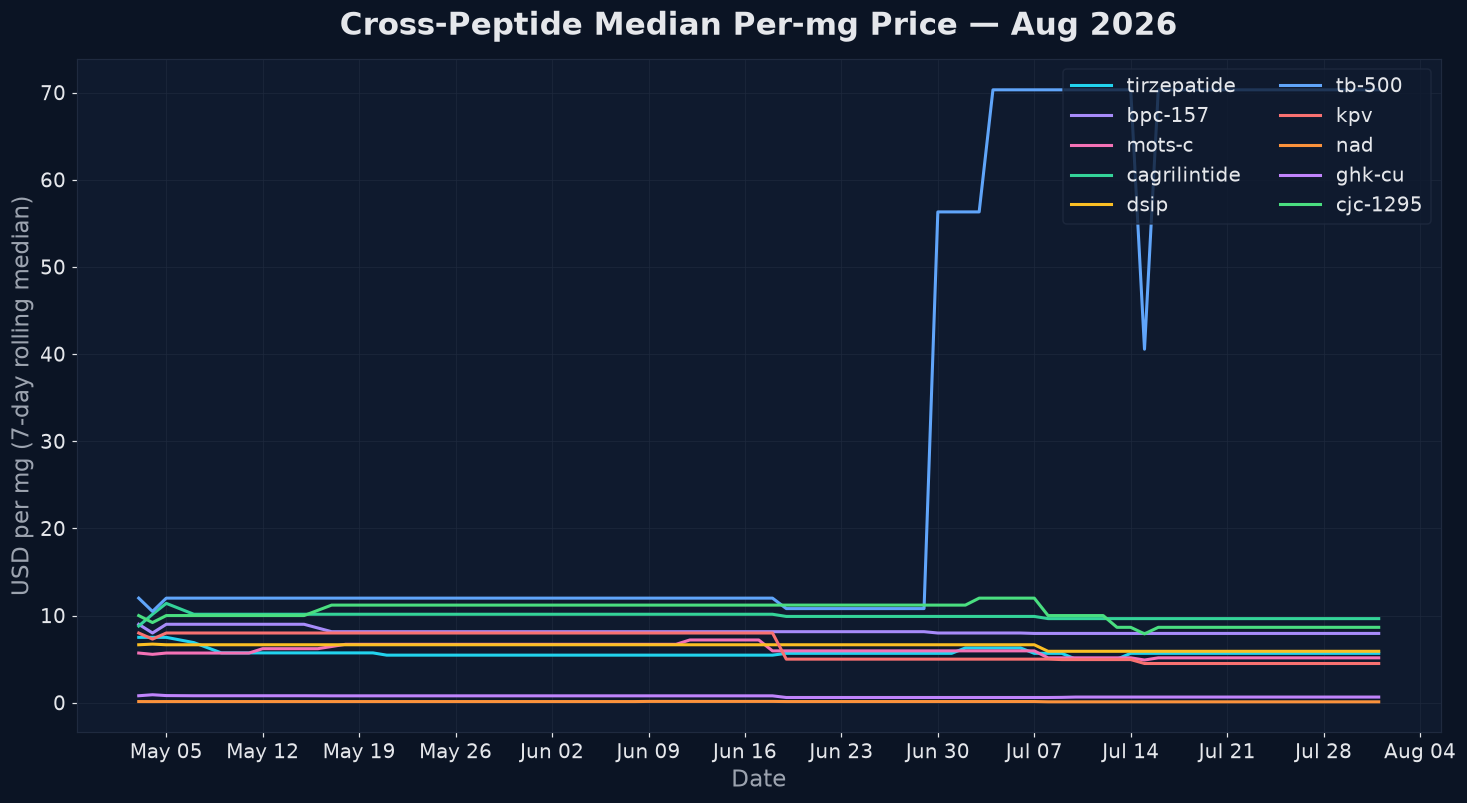
The chart above plots a 7-day rolling median per-mg price for the ten most-tracked peptides over the trailing 90-day window (August 3 – November 1, 2026). Three patterns stand out.
The commodity peptides stayed cheap and stayed put. NAD+ (around $0.10/mg) and GHK-Cu bulk vials (around $0.59/mg) traced essentially flat lines across the full window. These are the compounds sold in 50mg, 100mg, 500mg, 1000mg, and 1500mg vials, where the per-mg arithmetic collapses the price into commodity territory regardless of what any single vendor does. Tesofensine ($2.80/mg) and cartalax ($3.10/mg) sat just above them, below the main band.
The mid-market clustered in a $4–$11 band. KPV ($4.50/mg median), selank ($4.75), SLU-PP-332 ($4.80), BPC-157 ($4.90), PT-141 ($4.90), melanotan-2, semax, epitalon, pinealon, and melanotan-1 (all $5.00), 5-amino-1MQ ($5.20), MOTS-c ($5.40), kisspeptin, DSIP, and tirzepatide (all $6.00), retatrutide ($6.67), TB-500 ($7.03), thymosin alpha-1 ($7.10), sermorelin ($7.20), adamax, SS-31, and CJC-1295 (all $8.00), cagrilintide ($9.90), ipamorelin ($10.00), tesamorelin ($10.00), and AOD-9604 ($11.00) all landed inside it. That band is where most of the market lives, and it moved very little week to week.
Where medians moved, the like-for-like check mostly agrees on direction — except GHK-Cu. Comparing the first two weeks against the last two, in-stock blended medians held flat for BPC-157, NAD+, and sermorelin, fell for tirzepatide (-4.5%) and retatrutide (-7.4%), and rose for GHK-Cu (+6.2%). A like-for-like check — holding both vendor and vial size constant across the two halves of the window — supports the tirzepatide decline: no matched tirzepatide SKU went up. One vendor cut its 10mg, 20mg, and 60mg vials 15% each, a second cut its 10mg and 30mg vials 14% and 20%, and a third held its 10mg and 30mg vials flat while cutting its 60mg vial 18%.
GHK-Cu's rise does not survive the same test. Not one matched GHK-Cu SKU went up: one vendor cut its 2mg, 50mg, and 100mg vials 15% each, a second cut its 100mg vial 9% ($0.65 → $0.59), and a third held its 1mg and 50mg vials flat. The blended median rose because the mix of listings captured each day shifted. Retatrutide's matched SKUs moved in both directions — one vendor cut all four of its sizes 15%, a second cut its 30mg and 50mg vials 10% and 9% while raising its 20mg vial 10%, and a third raised its 10mg vial 25% while holding its 30mg vial flat.
One pattern repeats across compounds: the same vendor cut every matched SKU it carried by almost exactly 15% — in tirzepatide, retatrutide, and GHK-Cu alike — which reads as a catalog-wide repricing rather than compound-specific moves. That is the most important methodological caveat in this report: vendor coverage moved from 7 vendors and 53 compounds in August to 7 and 50 in September, then 7 and 55 in October, and when the set of vendors and listings being captured changes, the median changes with it — no vendor has to touch a price tag. Blended medians describe what a buyer could see on a given day. The matched-SKU check is what tells you whether anyone actually repriced.
Per-Peptide Deep Dives
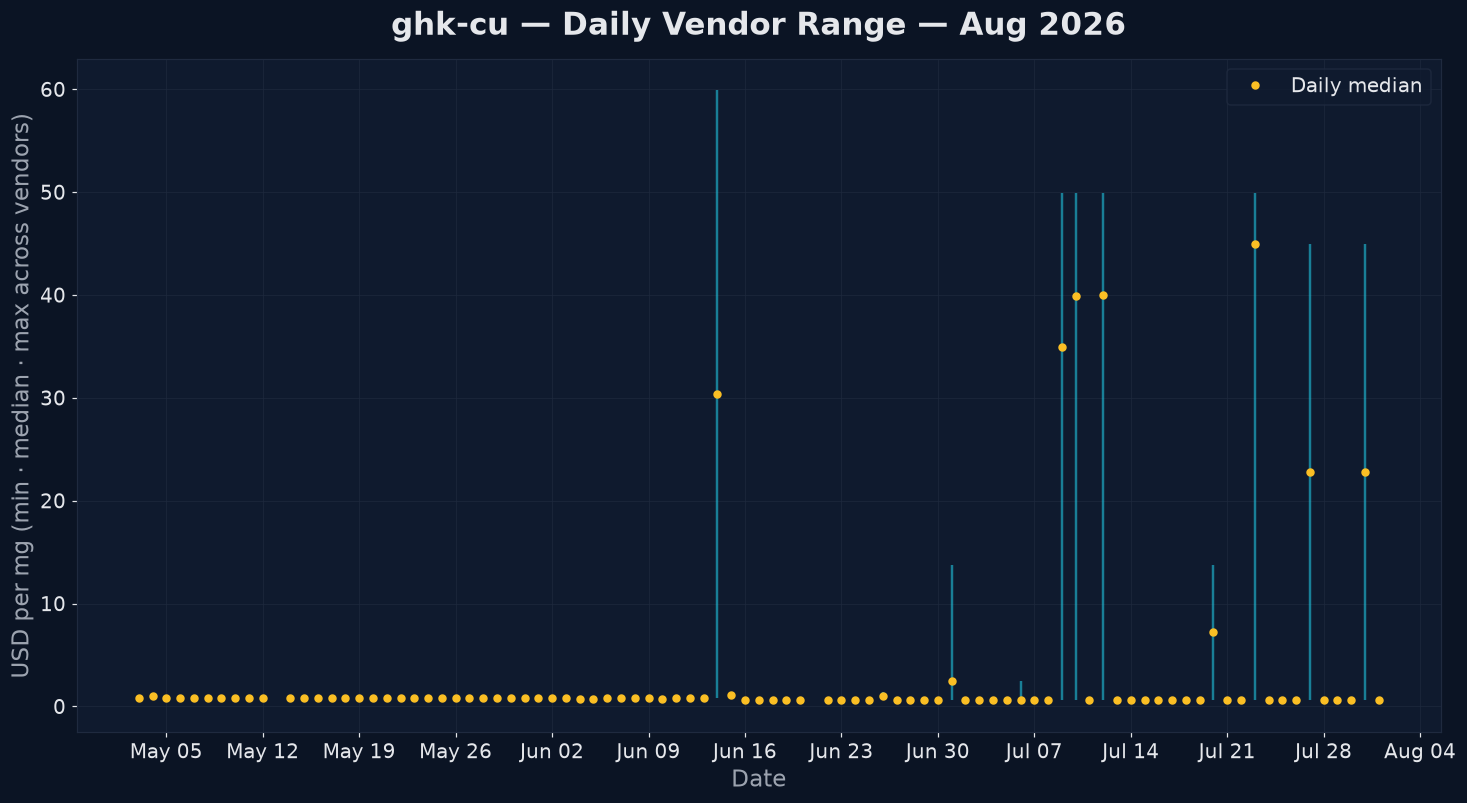
Each of the six peptides below has its own daily-range chart. The vertical wicks show the min-to-max per-mg price across all vendors on that day; the yellow dots are the daily median. No vendor lines, no vendor labels — this is supply-side dispersion only.
Tirzepatide
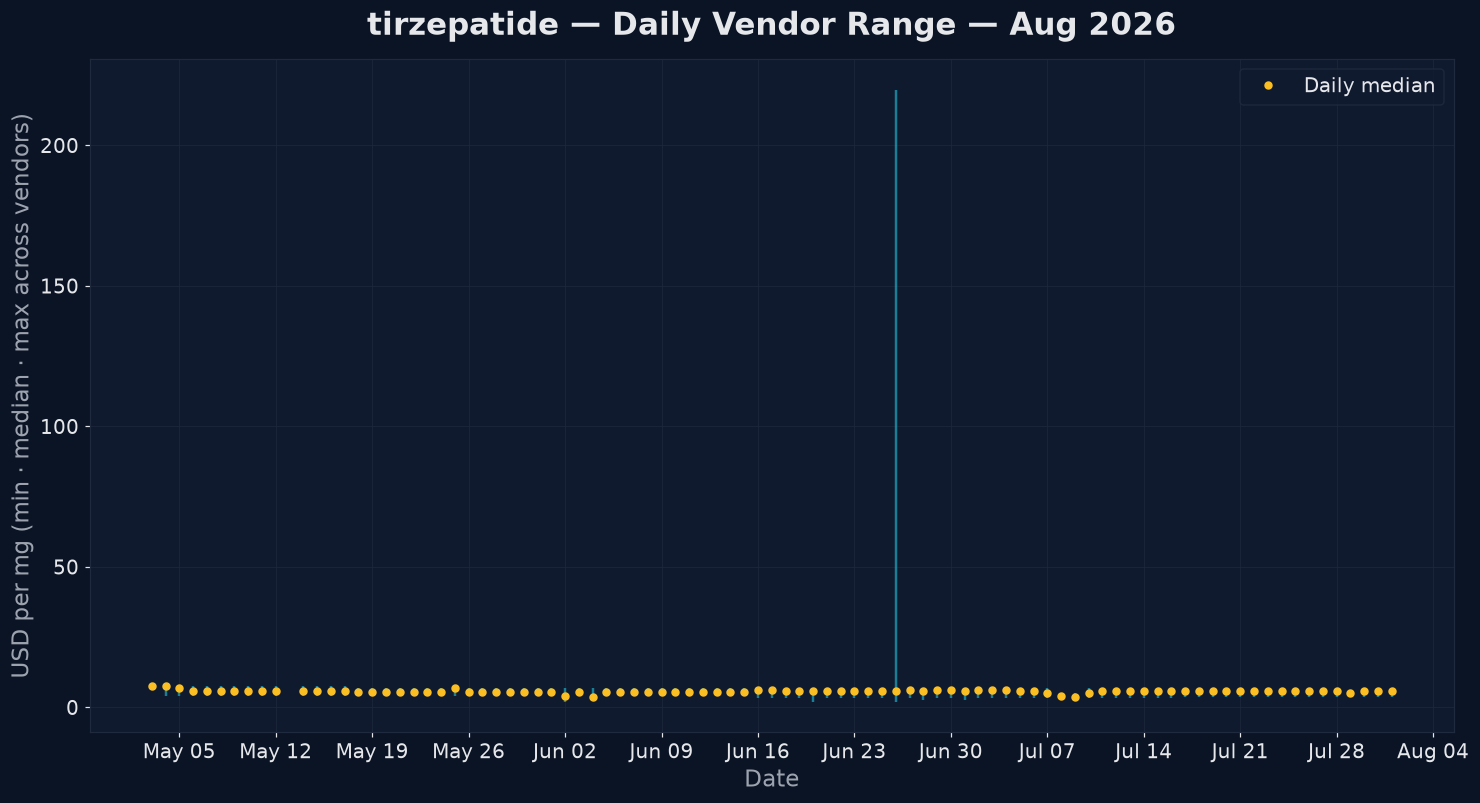
- Observations: 504 across 6 vendors (24 distinct SKUs)
- Median per-mg: $6.00
- Range across full window: $1.27 – $10.50 per mg (95th percentile: $9.00)
- Daily-median pricing changes (>0.5%): 27 across 90 transitions
- OOS rate: 1.2%
Tirzepatide is the most-tracked peptide in the dataset at 504 observations — nearly double the next compound, GHK-Cu, at 258 — and it carries the second-lowest stockout rate of any deep-dive peptide at 1.2%, behind only sermorelin. Supply is deep enough that no shortage pressure is visible anywhere in the window: the 30mg tier was never out of stock across 235 observations, and the 10mg tier was dark in 1.3% of its 239.
The range is contained. The top is $10.50/mg on a 10mg vial, and 95.2% of all observations priced at or below $10/mg. The genuine structure is vial-size tiering: 10mg vials ran a $6.90 median, 30mg vials $5.33, and 60mg vials $2.58, with the window's $1.27/mg low also on a 60mg SKU. Per-mg cost falls roughly 2.7× from the 10mg tier to the 60mg tier.
For ranked vendor options, see Best Tirzepatide Vendors.
Tirzepatide is the active ingredient in approved finished pharmaceutical products. The pricing in this dataset is for research-chemical compounded forms, which are not FDA-approved.
Retatrutide

- Observations: 178 across 6 vendors (35 distinct SKUs)
- Median per-mg: $6.67
- Range across full window: $2.18 – $12.50 per mg (95th percentile: $9.67)
- Daily-median pricing changes (>0.5%): 56 across 90 transitions
- OOS rate: 9.0%
Retatrutide has the second-noisiest daily median in the deep-dive set — 56 moves greater than 0.5% across 90 day-to-day transitions, meaning the median shifted on well over half of all comparable days. That is a mechanical effect more than a market one: six vendors carrying 35 SKUs — the most SKUs of any compound in the dataset — means any single listing going in or out of stock swings the median measurably.
The absolute range is contained — $2.18 to $12.50/mg, under 6×, with 98.9% of observations at or below $10/mg; the $12.50 figure was a 10mg listing that was dark at capture, and the in-stock maximum was $11.00. Vial sizes ran from 5mg to 100mg, and the tiering is steep: the 30mg tier carried the bulk of observations (103) at an $8.33 median, while 50mg and 60mg vials ran $4.35 and $3.63. The stockouts sit almost entirely outside the 30mg tier, which was never out of stock — against 23.8% for the 10mg tier and 25.0–33.3% for the 24mg, 50mg, 60mg, and 100mg tiers. Retatrutide remains an investigational molecule and supply is visibly thinner than tirzepatide's.
For ranked vendor options, see Best Retatrutide Vendors.
Retatrutide is investigational and not FDA-approved. All pricing is for research-grade material.
BPC-157

- Observations: 122 across 6 vendors (11 distinct SKUs)
- Median per-mg: $4.90
- In-stock range: $2.40 – $4.90 per mg (full-window max $11.00 — out-of-stock 5mg listings)
- Daily-median pricing changes (>0.5%): 17 across 90 transitions
- OOS rate: 10.7%
BPC-157's stockout rate fell sharply against the prior window — 10.7% of its vendor-day observations showed the product unavailable, down from 31.3% — and it now ranks sixth among compounds with at least 30 observations rather than second. The improvement is mostly a composition change: the 5mg listings that drove the prior figure contributed just 9 observations this window, all of them out of stock.
The strain is not evenly distributed across vial sizes. The 10mg tier, with 100 observations, was never out of stock in the window, and the 20mg tier was in stock in all 6 of its observations. The thinner 30mg and 50mg tiers were dark in 3 of 5 and 1 of 2 observations respectively. A buyer's experience of BPC-157 scarcity depends almost entirely on which vial size they are shopping for.
The price picture is tight. Every in-stock observation priced between $2.40 and $4.90/mg, with the larger 20mg and 30mg vials at the bottom of that range; the $11.00/mg figures in the raw data are 5mg listings that were dark at capture. The daily median moved just 17 times in 90 transitions.
For ranked vendor options, see Best BPC-157 Vendors.
NAD+
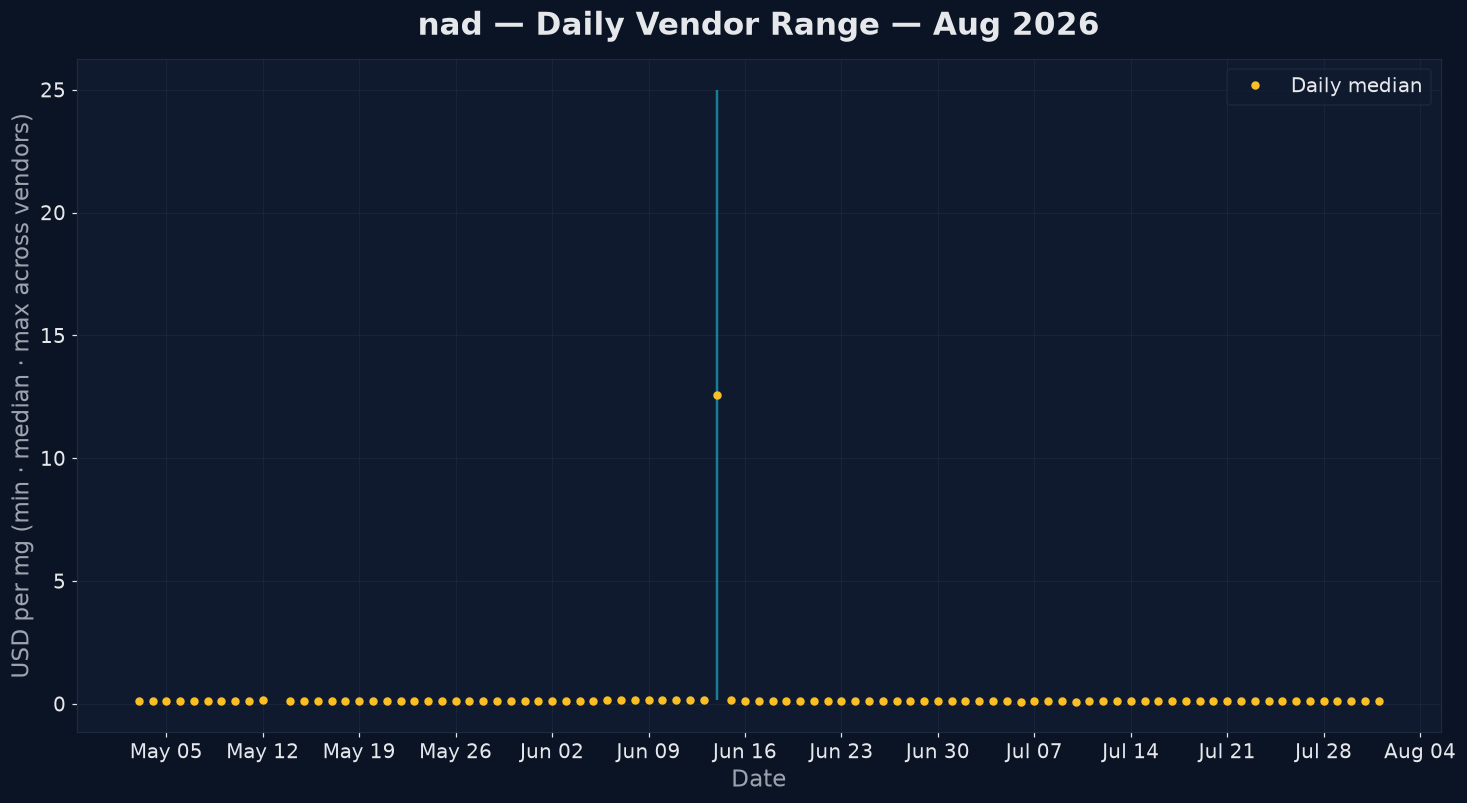
- Observations: 116 across 4 vendors (7 distinct SKUs)
- Median per-mg: $0.10
- Range across full window: $0.054 – $0.16 per mg (95th percentile: $0.115)
- Daily-median pricing changes (>0.5%): 30 across 90 transitions
- OOS rate: 2.6%
NAD+ is the cheapest well-tracked compound in the dataset by more than an order of magnitude, and the reason is vial size: 1000mg vials accounted for 93 of its 116 observations, 80.2% of the total. At that scale the per-mg cost lands in commodity territory — the 1000mg tier ran $0.104 to $0.110/mg with a $0.104 median. The 1500mg SKUs priced lower still at a $0.073/mg in-stock median, and supplied the window's $0.054 low.
The 30 daily-median moves are mostly mechanical. The dominant 1000mg tier barely moved, so the shifts come from the thinner 500mg and 1500mg listings entering and leaving each day's capture. Its 14.0% CoV puts it in the lower half of the leaderboard below.
Availability was strong. The 1000mg tier was never out of stock; the thin 500mg tier was dark in 2 of its 12 observations. The blended 2.6% rate is down slightly from 2.8% in the prior window.
Sermorelin
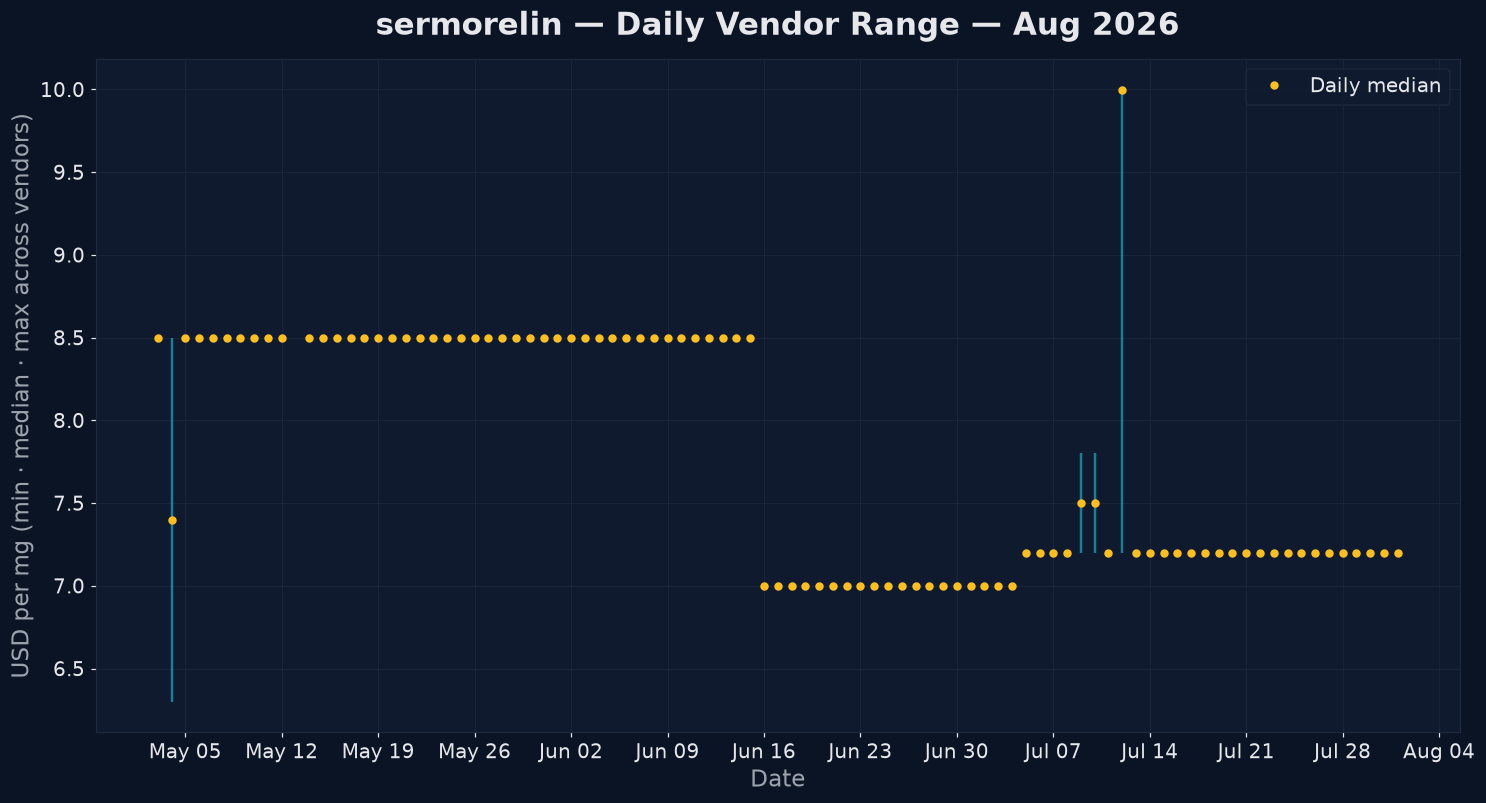
- Observations: 100 across 3 vendors (3 distinct SKUs)
- Median per-mg: $7.20
- Range across full window: $3.78 – $7.20 per mg (95th percentile: $7.20)
- Daily-median pricing changes (>0.5%): 14 across 90 transitions
- OOS rate: 1.0%
Sermorelin is the most stably priced peptide in the deep-dive set: the fewest daily-median changes (14 in 90 transitions), a 7.2% coefficient of variation, a 95th percentile equal to its median, and a 1.0% stockout rate — the lowest of the six. Every observation was a 10mg vial. The one vendor supplying 92 of the 100 observations held $7.20/mg for the entire window; the only figures below that came from eight observations at two other vendors, priced between $3.78 and $6.50/mg.
That pattern is consistent with a mature compound: a long history as a GHRH analog, an established compounded-pharmacy channel, and no supply events during the window.
GHK-Cu
- Observations: 258 across 5 vendors (12 distinct SKUs)
- Median per-mg: $0.65 (blended in-stock; bulk segment $0.59 — see below)
- Range across full window: $0.28 – $49.95 per mg (95th percentile: $39.95)
- Daily-median pricing changes (>0.5%): 59 across 90 transitions
- OOS rate: 21.7%
GHK-Cu is the clearest example in the dataset of a compound where a single median hides the market. It splits into two genuinely separate segments rather than a core plus outliers.
The bulk segment — 50mg and 100mg vials, 59.3% of observations — ran a $0.59/mg in-stock median across a $0.28–$0.90 range, and its 100mg tier was never out of stock across 129 observations. The small-vial segment — 1mg and 2mg SKUs, 40.7% of observations — priced at $21.00–$39.99/mg in stock, and its 1mg tier was out of stock 51.1% of the time (the $49.95/mg top of the range was a dark 1mg listing). These are not the same purchase. Small-vial GHK-Cu at those per-mg prices generally reflects cosmetic and topical formulations, where the buyer is paying for the finished product rather than the raw peptide mass.
The 59 daily-median moves — the most of any deep-dive peptide — are also a segment artifact: as the small-vial SKUs flick in and out of stock, the blended daily median jumps between the two segments. The same effect explains why GHK-Cu's blended median rose across the window while every matched bulk SKU fell or held.
Volatility Leaderboard
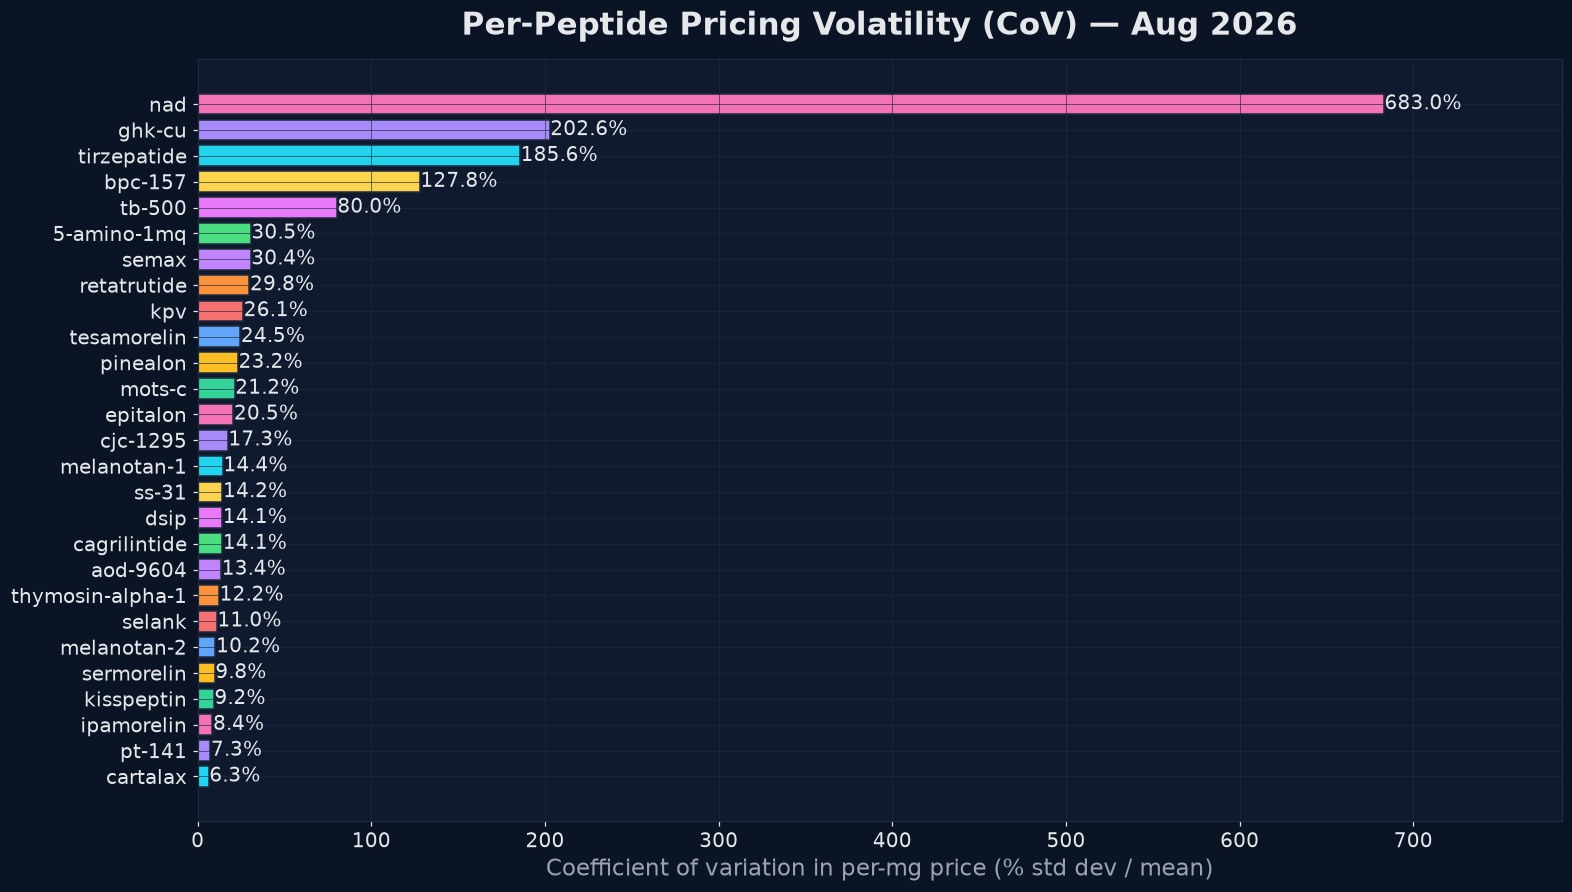
The chart plots the coefficient of variation (CoV) of per-mg pricing for every compound with at least 30 observations in the trailing-90-day window — 30 qualified. CoV = standard deviation ÷ mean, expressed as a percent. Higher = wider spread between vendors, SKUs, and time.
Reading the leaderboard:
- Above 60% CoV: GHK-Cu (117.5%), TB-500 (96.0%), SLU-PP-332 (60.1%). None of these is vendor disagreement on comparable product. GHK-Cu's figure comes from the cosmetic-vs-bulk split. SLU-PP-332 is thinly tracked (37 observations) across 5mg to 50mg vials from five vendors, with per-mg prices tracking vial size. TB-500's comes from a single 5mg listing recorded at $70.32/mg through August 5 and $7.03/mg from August 6 onward — a tenfold step on one day, the signature of a pack-size or listing change rather than a market-wide repricing.
- 30–60% CoV: 5-amino-1MQ (39.3%), retatrutide (34.6%), BPC-157 (33.6%), tirzepatide (32.7%). 5-amino-1MQ's figure is driven by the 10mg-vs-50mg vial split plus two out-of-stock listings recorded at implausibly low per-mg prices, BPC-157's by out-of-stock 5mg listings at $11.00/mg, and tirzepatide's by vial-size tiering. Retatrutide is the cleanest case of genuine vendor price dispersion here — the same 30mg vial ran from roughly $4 to $8.33/mg depending on the vendor.
- 15–30% CoV: adamax (25.4%), semax (23.8%), AOD-9604 (23.2%), SS-31 (22.0%), tesofensine (21.6%), CJC-1295 (20.2%), DSIP (17.3%), MOTS-c (17.1%), PT-141 (17.1%), tesamorelin (17.0%), selank (16.6%), ipamorelin (16.3%). The comparison-shopping zone — real spread between vendors on the same product. Semax's 10mg vial ranged from $2.46 to $7.50/mg across vendors, SS-31's 10mg vial from $2.76 to $8.00/mg, and AOD-9604's 5mg vial from $9.00 to $18.60/mg.
- Below 15% CoV: kisspeptin (14.5%), melanotan-2 (14.5%), NAD+ (14.0%), epitalon (13.8%), cagrilintide (11.8%), thymosin alpha-1 (10.8%), melanotan-1 (10.8%), KPV (8.8%), sermorelin (7.2%), pinealon (7.0%), cartalax (6.0%). Eleven of the 30 tracked compounds price within a tight band across every vendor in the cohort.
The practical read: a high CoV number on this chart is a prompt to check what is being compared, not automatically a signal that one vendor is overcharging. Sometimes it is vial size (5-amino-1MQ, tirzepatide), sometimes it is a cosmetic-versus-research channel split (GHK-Cu), sometimes it is a single listing change (TB-500) — and sometimes, as with retatrutide, semax, and SS-31, it is straightforward vendor price dispersion on the same thing.
Supply Patterns

The heatmap above shows OOS rate per peptide per ISO week. Darker = more vendor-days marked out of stock during that week.
Aggregate stockout rate for the window: 6.2%, meaning roughly one in sixteen vendor-day observations across the dataset showed a product as unavailable. That is a better supply picture than the preceding window, which ran at 8.3%.
The weekly trend was steady after a rough start. The window's worst reading came in its first week — 16.1% in the week of August 3. From the week of August 10 onward the dataset never rose above 8.0% in any week, and every October week ran between 3.5% and 6.4%, with the week of October 12 the window's best at 3.5%.
Concentration matters more than the aggregate. The compounds carrying sustained dark bands are SLU-PP-332 (27.0% OOS), GHK-Cu (21.7%), adamax (20.6%), SS-31 (17.9%), and PT-141 (15.6%). Below those five the drop is steep: BPC-157 at 10.7%, tesofensine at 9.2%, retatrutide at 9.0%, cartalax at 7.9%, and everything else under 7%. The dataset's 6.2% aggregate is not a market-wide scarcity signal — it is a handful of compounds under real pressure and a long tail that is broadly well-stocked.
Stockout patterns also interact with price. When one or two vendors go dark, the median per-mg price visible to buyers can drift simply because a cheap or expensive listing disappeared from the cohort — the same composition effect described in the cross-peptide section. GHK-Cu's 59 daily-median moves and retatrutide's 56 both trace back to stock flicker and listing mix rather than repricing. The price chart and the OOS chart are best read together.
What This Means for Buyers
Generic, evergreen guidance based on the patterns visible across the window:
Check vial size before concluding a vendor is expensive. This is the single largest source of apparent price difference in the dataset. Tirzepatide's per-mg cost fell roughly 2.7× from its 10mg tier to its 60mg tier. NAD+'s entire ~106× advantage over mid-market peptides is vial-size arithmetic. Retatrutide's 60mg tier priced at less than half its 30mg tier.
Check the channel too. Vial size explains most dispersion but not all of it. GHK-Cu's 1mg and 2mg cosmetic-format listings priced at $21.00–$39.99/mg in stock in the same window its 100mg research vials ran $0.59/mg. A premium-retail listing and a research-supply listing can look like the same product on a search results page.
Comparison shopping pays on some compounds and not others. Retatrutide, adamax, semax, AOD-9604, SS-31, and CJC-1295 showed 20–35% CoV — real vendor-to-vendor spread. Thymosin alpha-1, melanotan-1, KPV, sermorelin, pinealon, and cartalax all sat under 11%, where the delta between vendors is smaller than the difference shipping speed or COA documentation makes.
Availability is the binding constraint on a few compounds, not most. With SLU-PP-332 at 27.0% and GHK-Cu at 21.7% OOS, a buyer's practical problem on those compounds can be finding stock rather than finding a good price. But the constraint is often tier-specific: GHK-Cu's 1mg vials were dark more than half the time while its 100mg vials never went out of stock, and BPC-157's 10mg vials never went out of stock at all.
Per-mg, not per-vial. Vial sizes in this dataset ranged from 1mg to 5,000mg. Comparing dollar prices without normalizing to per-mg is the largest avoidable source of overpaying in this market.
Premium small-vial SKUs distort every summary statistic. When a peptide shows a max per-mg price 5–10× its median, it is almost always a 1mg, 2mg, or 5mg trial-size or cosmetic SKU at full retail. GHK-Cu's 1mg tier priced roughly 51× above its 100mg tier for what is nominally the same compound.
End-of-month vs. mid-month. This window was not granular enough to confirm end-of-month promotional pricing as a reliable pattern. Some vendors run periodic clearance events; others price flat. Future refreshes will track this more carefully.
If you want a vendor starting point without doing your own daily price tracking, our Best Peptide Vendors of 2026 compares the top-rated vendors on price, COA documentation, shipping reliability, and reputation. That ranking is updated continuously as data shifts.
Methodology Limitations
In the spirit of editorial independence, the limitations of this dataset:
- The window covers August 3 – November 1, 2026 (trailing 90 days), with data captured on 91 of those days. Each monthly refresh rolls this window forward, so the figures always describe the most recent quarter of live prices rather than a fixed calendar quarter.
- Cohort composition changed during the window. Coverage moved from 7 vendors and 53 compounds in August to 7 and 50 in September, then 7 and 55 in October, with 8 distinct vendors appearing across the full window. When the captured vendor set changes, blended medians move without anyone repricing. This report includes a matched-SKU check (same vendor, same vial size, both halves of the window) to separate the two, and the cross-peptide section reports where the two disagree.
- Per-mg normalization assumes purity parity. It does not hold. Two vendors selling 10mg of "BPC-157" may ship different actual peptide quantities depending on assay results. This dataset takes the listed mg figure at face value and does not adjust for COA-reported purity.
- Bundle SKUs were normalized as
mg_per_vial × vial_count. This is the right adjustment for buyers comparing per-mg cost, but it slightly compresses the apparent vendor-spread for peptides where bundle pricing varies significantly per-vial. A listing whose recorded pack size changes mid-window — as appears to have happened on one TB-500 listing on August 6 — shows up as a step change in per-mg price. - Cosmetic, topical, and premium-retail listings are priced alongside research-grade vials. GHK-Cu is the clearest case — its small-vial SKUs are finished consumer products, not raw research material, but they normalize into the same per-mg column. This inflates both the range and the CoV for any compound sold through both channels.
- Eight vendors is a meaningful slice but not exhaustive. The cohort skews toward English-language US-shipping research-grade vendors. Non-US vendors and prescription-only compounded sources are not in this dataset.
- Anonymization is an editorial choice, not a privacy requirement. All prices in this dataset were public on vendor websites at the time of capture. We anonymize because it lets us report on industry-wide patterns without our affiliate relationships influencing the analysis.
- The OOS flag reflects what the vendor's website displayed. Some vendors mark a SKU as "available — backorder 7 days," which we treat as in-stock; others show "out of stock" the moment inventory hits zero. Inter-vendor stock-status reporting is not strictly comparable.
- Thin tiers carry outsized weight in blended rates. Retatrutide's 9.0% stockout rate sits entirely outside its 30mg tier, which, with 103 observations, was never out of stock. GHK-Cu's 21.7% sits almost entirely in its 1mg tier. Any figure computed across a peptide's full SKU set should be read alongside the per-tier breakdown.
Coming Next
This report refreshes monthly, with each version covering a rolling trailing-90-day window on full daily scraper cadence. The chart set and anonymization scheme stay constant across refreshes so successive versions are directly comparable.
Planned additions to future refreshes:
- Vial-size-normalized medians — per-mg figures computed within matched SKU tiers, so headline numbers stop moving when the SKU mix changes
- Channel segmentation — separating premium-retail listings from research-supply listings before computing dispersion, so CoV measures vendor disagreement rather than market structure
- Period-over-period delta for every peptide with a stable vendor cohort across successive windows
- End-of-month vs. mid-month pricing pattern test
- Stockout-to-price-recovery lag — how many days between OOS-onset and post-restock pricing returning to baseline
Where to buy if you're researching options
For most readers landing here from FDA / vendor / pricing coverage, the two highest-utility next-stops on this site are:
- Retatrutide for sale — vendor price comparison — vendor pricing, COA verification, vial-size tradeoffs for the highest-search-volume peptide of 2026
- Best Peptide Vendors of 2026 — head-to-head vendor comparison ranked by price, COA documentation, and reputation